Forex Risk Management: The Complete Account-Survival System
Risk per trade, daily limits, correlation and drawdown recovery: a practical system for keeping a forex account alive.
Reviewed by Hà Ngọc Lộc· Senior SEO Editor
For many retail traders, the journey into the foreign exchange market follows a predictable, frustrating cycle. You study technical analysis, identify high-probability chart patterns, execute a string of profitable trades, and build momentum. Then, in a single session—or over a brutal two-day streak—a cluster of losses wipes out weeks of gain and destroys your personal capital balance. Sound familiar?
This cycle does not happen because your strategy lacks technical indicators or entry setups. It happens because of a breakdown in forex risk management. Without an objective risk management system, trading capital is continually exposed to mathematical asymmetry, emotional over-leveraging, and unpredictable volatility events.
This full guide details the exact account-survival framework used by professional traders to preserve capital, control drawdown, and eliminate the systemic habits that lead to blown accounts. Whether you are trading personal funds or preparing for proprietary evaluation environments, mastering these risk protocols is non-negotiable.
1. The Math of Drawdowns and Asymmetric Loss
The core imperative of risk management in forex trading stems from a simple mathematical reality: loss recovery is non-linear. When an account incurs a loss, the percentage gain required to return to breakeven is always larger than the percentage lost.
If you lose 10% of a $10,000 balance, your capital decreases to $9,000. Returning to $10,000 requires a $1,000 profit, which is an 11.1% gain on your remaining $9,000 balance. As drawdowns deepen, the required recovery percentage grows exponentially.
| Account Loss (%) | Remaining Capital ($10k Starting) | Required Gain to Breakeven (%) | Psychological Recovery Level |
|---|---|---|---|
| 5% | $9,500 | 5.26% | Manageable |
| 10% | $9,000 | 11.11% | Manageable |
| 20% | $8,000 | 25.00% | Challenging |
| 30% | $7,000 | 42.86% | Severe Stress |
| 50% | $5,000 | 100.00% | Extreme / Low Probability |
| 75% | $2,500 | 300.00% | Near Terminal |
When an account experiences a 50% loss, you must double your remaining equity just to get back to where you started. At a 75% drawdown, you need a 300% return. Under this level of psychological pressure, traders almost universally abandon their rules, increase leverage, revenge trade, and destroy the remaining capital entirely.
To break this destruction cycle and protect personal equity, you must establish hard risk parameters before placing trades. If you have experienced repeated drawdowns in your personal account, review our detailed guide on how to restructure your habits and Learn How To Stop Blowing Trading Accounts.
2. Position Sizing Equations & Risk Protocols
The single most powerful tool in your forex risk management strategies arsenal is scientific position sizing. Most un profitable traders select lot sizes based on arbitrary feelings or static rules (such as always trading 1.0 lot) regardless of stop-loss distance or asset volatility.
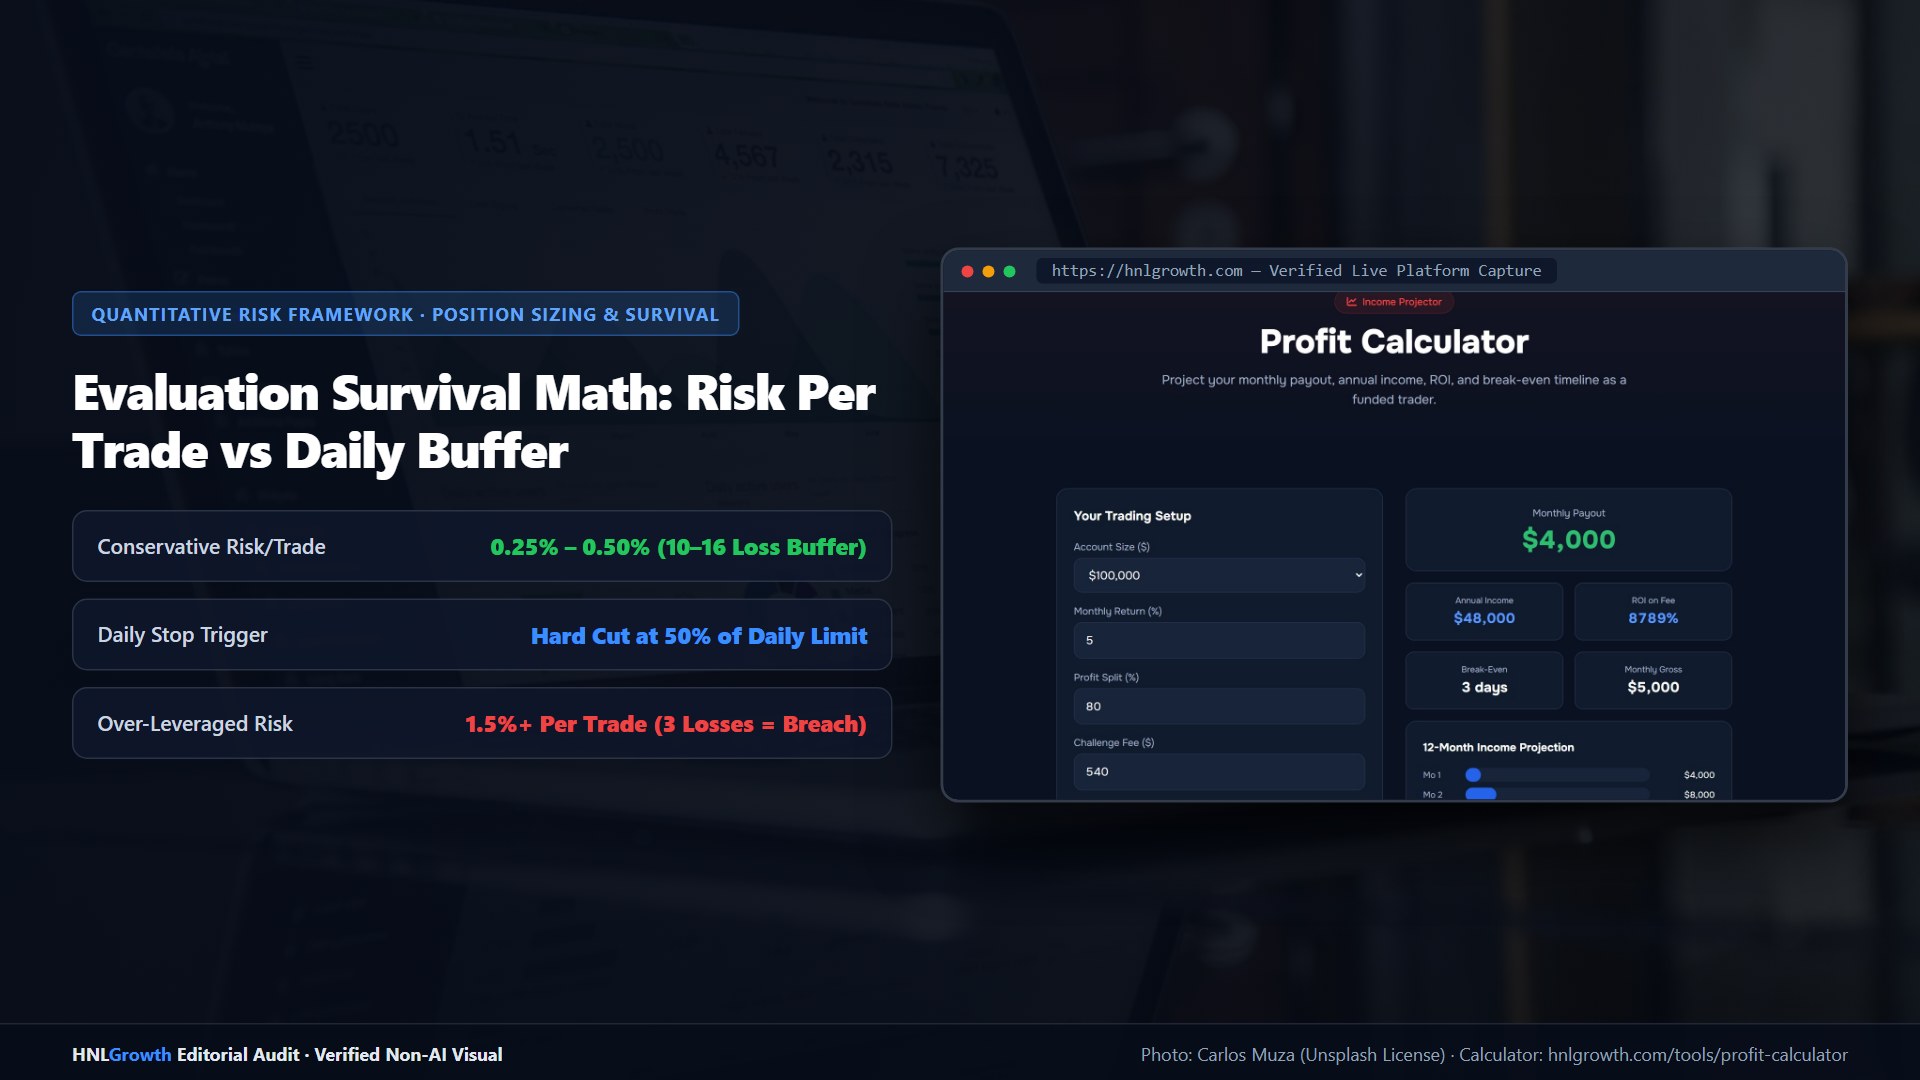
Professional risk control requires fixing the maximum cash value at risk per trade to a precise percentage of current equity (typically 0.5% to 2.0%), and adjusting the trade size based on the specific stop-loss distance.
The Standard Position Sizing Formula
To calculate the correct position size for any forex trade, use the following core equation:
Position Size (Lots) =
[Account Equity ($) × Risk Percentage (%)] / [Stop Loss (Pips) × Pip Value per Standard Lot ($)]
Worked Calculation Example
- Account Balance: $20,000
- Maximum Risk per Trade: 1.0% ($200)
- Currency Pair: EUR/USD (where 1 standard lot = $10 per pip)
- Technical Stop Loss: 25 pips
Plugging these figures into the formula gives:
Position Size = $200 / (25 pips × $10/pip) = $200 / $250 = 0.80 Standard Lots (80,000 units)
If market setup conditions require a wider stop loss of 50 pips due to structural volatility, you do not double your monetary risk. Instead, you scale down your position size:
Position Size = $200 / (50 pips × $10/pip) = $200 / $500 = 0.40 Standard Lots (40,000 units)
By adjusting position sizes dynamically based on price structure, your maximum downside remains fixed at $200 regardless of whether your stop loss is 10 pips or 100 pips. For a broader breakdown of capital longevity models, Learn Trading Capital Preservation.
3. Risk Management Strategies for Volatile Markets
Standard fixed-pip risk management fails when trading instruments with fluctuating volatility or trading multiple correlated pairs simultaneously. Advanced risk management in forex trading requires adapting to volatility cycles and managing cross-asset dependencies.
Utilizing Average True Range (ATR) for Adaptive Stop Loss Placement
Arbitrary 10-pip or 20-pip stops frequently fail because they do not account for market regime changes. Placing a 15-pip stop on a quiet Asian session range might be appropriate, but placing the same 15-pip stop on a volatile London open or high-impact news event guarantees premature stop-outs.
The Average True Range (ATR) indicator measures market volatility over a designated period (commonly 14 periods). Incorporating ATR into your stop placement ensures your trades have sufficient breathing room relative to current market conditions:
- Low Volatility (ATR = 12 pips): Stop loss set at 1.5× ATR = 18 pips. Position size scales up accordingly.
- High Volatility (ATR = 40 pips): Stop loss set at 1.5× ATR = 60 pips. Position size scales down accordingly.
When trading commodities or volatile instruments like spot gold alongside major forex pairs, fixed rules must adapt to wild swings. To see how these principles apply to specific high-beta pairs, Learn XAUUSD Risk Management.
Managing Currency Pair Correlations
A frequent hidden risk in retail portfolios is position correlation. If a trader buys EUR/USD, GBP/USD, and AUD/USD simultaneously, they are not executing three independent, diversified trades. Because all three setups depend on US Dollar weakness, the trader has effectively taken a single 3x concentrated bet against the USD.
| Currency Pair Combination | Typical Correlation Coefficient | Portfolio Impact | Risk Control Action |
|---|---|---|---|
| EUR/USD & GBP/USD | +0.80 to +0.95 (High Positive) | Doubles USD exposure | Split risk budget (e.g., 0.5% each) |
| EUR/USD & USD/CHF | -0.85 to -0.98 (High Negative) | Opposing bets neutralize edge | Avoid holding both simultaneously |
| AUD/USD & NZD/USD | +0.85 to +0.92 (High Positive) | Doubles commodity currency exposure | Treat as a single asset group limit |
4. Behavioral Circuit Breakers & Daily Limits
Even mathematically ideal position sizing breaks down when human psychology encounters consecutive losses. The human brain interprets trading losses as threats, often triggering fight-or-flight responses that lead to revenge trading, removing stop losses, or over-leveraging to recover losses quickly.
To prevent psychological spiral, professional frameworks implement mechanical behavioral circuit breakers.
The Account Survival Ruleset
- Daily Loss Limit (DLL): Cap maximum permissible daily loss at 2% to 3% of total account value. If hit, platform access is closed for the remainder of the session.
- Max Consecutive Loss Pause: After 3 consecutive losing trades, trading must stop for a mandatory 24-hour evaluation period to audit setup execution versus emotional impulse.
- Weekly Drawdown Threshold: If account equity drops by 5% in a single trading week, reduce position size per trade by 50% until equity re-attains previous highs.
- Hard Stop Enforcement: Every order must feature a hard stop loss attached at entry. Moving stops wider during active trades is strictly prohibited.
5. Formalizing Risk in Proprietary & Funded Trading
For traders seeking to transition from risking personal balance equity to operating within capitalized evaluation environments, strict risk parameters move from optional discipline to hard, system-enforced boundaries.
Proprietary trading firms design evaluation programs around strict drawdown limits and daily loss constraints. These institutional rules mirror professional risk desk management and eliminate fatal retail trading habits.
How Institutional & Evaluation Models Rules Structure Risk
Leading evaluation programs categorize risk into distinct boundaries that traders must operate within:
- Two-Step Evaluations (e.g., High Stakes): Incorporate fixed daily loss thresholds and total maximum drawdown limits alongside profit targets across distinct qualification phases.
- Multi-Stage Routes (e.g., Bootcamp): Feature step-by-step risk management benchmarks, where maintaining strict drawdowns allows progression through multi-level evaluation stages.
- One-Step Direct Growth (e.g., Hyper Growth): Provide a streamlined single-phase route with specific program leverage, available assets, and pre-set max loss conditions.
- Futures Programs (e.g., Day Trade & Swing Options): Utilize End-of-Day (EOD) loss limits and consistency criteria to ensure trades mirror exchange-traded risk requirements.
Understanding exactly how static equity baselines compare to trailing parameters is important before attempting any evaluation or live risk management environment. To examine these mechanisms in depth, See How Funded-Account Rules Formalize This Risk.
6. Personal Risk Audit & Checklist
Before launching your platform and taking your next trade setup, review this account-survival checklist to confirm your trading plan aligns with institutional standards:
- ☐ Monetary Risk Defined: Is exact dollar risk fixed at ≤ 1-2% of total equity?
- ☐ Stop Loss Placed: Is a hard stop loss placed at entry according to technical structure or ATR?
- ☐ Position Size Computed: Was lot size calculated specifically for this trade's pip distance?
- ☐ Correlation Checked: Are you avoiding stacking duplicate exposure across correlated pairs?
- ☐ Daily Limit Active: Is your daily circuit breaker active if trading hits maximum daily loss?
- ☐ Event Risk Cleared: Have high-impact economic news releases been reviewed?
Further reading: BIS Triennial FX Survey · FCA guidance on CFDs and leveraged products.
A tiered drawdown protocol that removes in-the-moment decisions
Defining three response thresholds and the mandatory action at each
A drawdown protocol must be written before losses occur. Rules revised mid-drawdown have a known failure mode: they are relaxed at the exact moment they matter most.
| Tier | Drawdown (peak-to-trough) | Mandatory action |
|---|---|---|
| Tier 1 | 5% | Reduce position size by 50% for all remaining trades that session |
| Tier 2 | 10% | Stop trading for the session; review trade journal before next session |
| Tier 3 | 15% | Halt trading for the week; complete a formal strategy review before returning |
These thresholds are starting points. A higher-frequency strategy with a 55% win rate may accept a 5% daily drawdown as within normal variance. A swing strategy with wide stops may reach Tier 1 after two trades. Calibrate to your strategy's documented variance, not to a generic rule.
The asymmetric math of recovery: why a 25% loss requires more than a 25% gain
Table: Gain required to recover from drawdown
| Drawdown | Recovery gain required |
|---|---|
| 5% | 5.3% |
| 10% | 11.1% |
| 15% | 17.6% |
| 20% | 25.0% |
| 25% | 33.3% |
| 30% | 42.9% |
| 40% | 66.7% |
| 50% | 100.0% |
A 25% drawdown requires a 33.3% gain from the reduced equity base to reach a new high. The Tier 1 position-size reduction is structurally important because it reduces the denominator: a smaller active account needs a smaller absolute gain to recover, and smaller position sizes mean the strategy can remain operational rather than burning remaining capital.
Choosing a stop-loss method that matches market structure
Structural stops: placing the exit at the price that invalidates the trade idea
A structural stop is placed just beyond the nearest support level, demand zone, or swing low that the trade thesis depends on. If a long EUR/USD position is based on a bounce from a demand zone at1.0820, the stop belongs below that zone — at the price where the structure is clearly broken, not at a round number above it.
This method produces a stop distance that reflects actual market conditions. It is the preferred method for any account size where the resulting position size remains above the broker minimum.
Volatility-adjusted stops: using average range to avoid noise-triggered exits
Stops placed too close to entry are triggered not by the trade being wrong but by normal intraday noise. Average True Range (ATR), calculated over14 periods, quantifies the average candle movement over that window.
A widely applied rule: set the stop at 1.5–2× the 14-period ATR below entry. If EUR/USD has a 14-period ATR of 60 pips, a 1.5× stop is 90 pips. The position size must be reduced accordingly to maintain dollar risk at1%. ATR widens around news events and narrows in quiet conditions, making this a structurally honest alternative to fixed-pip placement.
Fixed-dollar stops: the limited case where they apply
A fixed-dollar stop is appropriate only when account size is too small for a structural stop to produce a viable position size — for example, a $1,000 account risking1% ($10) where a 20-pip structural stop would require a 0.05-lot position, below many brokers' 0.01-lot minimum. Even in this case, the stop distance has no relationship to where the trade idea is actually wrong. It is a capital management constraint, not a technical one.
Forex Risk Management: Your Questions Answered
What is the golden rule of forex risk management?
The foundational rule of forex risk management is to never risk more capital on a single trade than you can comfortably lose without emotional impairment or structural account damage—typically between 1% and 2% of total account equity per trade.
How do you calculate lot size based on account risk?
Divide your dollar amount at risk (Account Equity × Risk %) by the product of your stop-loss distance in pips and the dollar value per pip for a standard lot. This adjusts your lot size dynamically while keeping monetary risk fixed.
What is the difference between static and trailing drawdown?
A static drawdown sets a permanent loss threshold fixed to your starting capital balance (or reset threshold). A trailing drawdown moves upward as your account balance or high-water equity increases, locking in the gap behind your highest point achieved.
How does leverage impact risk in forex trading?
Leverage increases purchasing power, allowing larger position sizes with less margin required. However, leverage acts as a multiplier: while it amplifies gains when trades succeed, it accelerates losses when position sizes are oversized relative to total balance equity.
Methodology & Evidence Limitations
This guide prioritizes risk principles, capital protection math, and standardized risk controls. Performance outcomes in forex trading depend on individual discipline, market volatility, execution speed, and broker environment conditions.
Program terms, evaluation parameters, loss limits, leverage allowances, and program specifications for third-party platforms or funding evaluation providers are subject to change. Readers should verify current rules directly on official platforms such as The5ers Official FAQs before entering paid evaluations or trading live simulated environments.
Compare How Prop Firms Enforce Drawdown Limits →
Related The5ers Guides
Related Guides
Sources & verification
- Last checked
- Written by
- HNL Growth Team
- Reviewed by
- Hà Ngọc Lộc
- Length
- 10 min read · 2,332 words
Rules, prices and payout terms on this page were checked against the official websites, help-centre articles and published terms of the firms mentioned, on the date above. Prop firms and brokers change conditions often — confirm the current version on the official site before you buy or deposit. Read our editorial methodology and affiliate disclosure.
Official sources & documentation verified
- BIS Triennial FX Survey(bis.org · Official Regulator)
- FCA guidance on CFDs and leveraged products(fca.org.uk · Official Regulator)
Explore Related Hubs & Free Trading Tools
Ready to Start Your Funded Trading Journey?
HashHedge reports $11M+ paid to traders and lists a 4.7/5 Trustpilot rating (check current figures on Trustpilot). Compare HashHedge challenge plans, drawdown rules, and payout terms — apply code ha25 for the current discount.
Risk disclaimer: Challenge fees are non-refundable if you breach the rules. Prop trading involves significant financial risk. Past performance in a simulated environment does not guarantee results on a funded account. Only purchase if you understand the rules fully and can afford to lose the fee. Affiliate disclosure: HNL Growth earns a commission when you purchase a HashHedge challenge through links on this page.