Martingale Trading Risks: Why Increasing Size After Losses Fails
Doubling size after losses turns a normal losing streak into a blown account. The math behind martingale and why prop firms ban it.
Reviewed by Hà Ngọc Lộc· Senior SEO Editor
The allure of never closing a trading sequence in a net loss is the primary driving force behind the Martingale trading strategy. Dating back to 18th-century France, where it originated as a casino betting framework, Martingale relies on a simple premise: double your position size after every losing trade so that a single winning trade recovers all previous losses plus yields a profit equal to the original trade size.
In retail Forex and futures trading, Martingale mechanics are frequently packaged into automated trading robots (Expert Advisors or EAs), custom grid scripts, or manual recovery protocols. While this methodology often produces flat equity curves and high win rates over brief periods, it hides a catastrophic tail risk. Rather than establishing a genuine structural edge—such as those analyzed in our guide to Learn Smart Money Concepts Trading—Martingale trades statistical probability for systemic account destruction.
This full guide breaks down the mathematical mechanics, geometric exposure curves, liquidity constraints, and psychological traps that make Martingale strategies unsustainable for serious market participants.
1. Mathematical Mechanics: The Mechanics of Position Doubling
To understand why Martingale fails, one must examine its core mathematical equation. In a traditional 1:1 risk-to-reward ratio setup, a trader opens a trade with position size $S_1$. If trade $1$ hits a loss, trade $2$ is opened at size S_2 = 2 × S_1. If trade $2$ fails, trade $3$ is opened at S_3 = 2 × S_2 = 4 × S_1.
In general terms, for any given sequence step $n$, the trade size $S_n$ is expressed as:
S n = S1 × 2(n - 1)
The total cumulative volume exposure ($V_{total}$) committed across $n$ steps is represented by:
V total = S1 × (2n - 1)
The mathematical fatal flaw lies in the ratio between cumulative risk and net reward. Regardless of how deep the losing streak extends—whether it reaches 5, 8, or 12 consecutive losses—the net profit upon eventual victory remains strictly locked at the profit value of the initial base lot ($S_1$).
Worked Example: The Exponential Progression Table
Consider a standard Forex scenario on EUR/USD. A trader starts with a initial lot size of 0.10 lots ($1.00 per pip) with a fixed stop loss and take profit target of 20 pips ($20 initial target). The starting account balance is $10,000, and standard broker leverage requires approximately $330 in margin per full lot (assuming 1:30 leverage).
| Step (n) | Trade Size (Lots) | Pip Risk / Target | Trade Risk ($) | Cumulative Loss ($) | Required Margin ($) | Net Profit on Win ($) |
|---|---|---|---|---|---|---|
| 1 | 0.10 | 20 pips | $20 | $20 | $33 | $20 |
| 2 | 0.20 | 20 pips | $40 | $60 | $99 | $20 |
| 3 | 0.40 | 20 pips | $80 | $140 | $231 | $20 |
| 4 | 0.80 | 20 pips | $160 | $300 | $495 | $20 |
| 5 | 1.60 | 20 pips | $320 | $620 | $1,023 | $20 |
| 6 | 3.20 | 20 pips | $640 | $1,260 | $2,079 | $20 |
| 7 | 6.40 | 20 pips | $1,280 | $2,540 | $4,158 | $20 |
| 8 | 12.80 | 20 pips | $2,560 | $5,100 | $8,316 | $20 |
| 9 | 25.60 | 20 pips | $5,120 | $10,220 (BUST) | Exceeds Capital | $20 |
As demonstrated in the table above, by trade step 8, the trader is risking $2,560 on a single position, carrying a cumulative loss of $5,100, and committing over $8,000 in account margin—all to net a tiny profit of $20. On step 9, the required position size exceeds total account equity, causing complete capital destruction (margin call and liquidation).
2. The 5 Core Martingale Trading Risks Explained
Risk 1: The Fallacy of Finite Capital vs. Infinite Risk (Gambler's Ruin)
The mathematical theory behind Martingale guarantees eventual success only under one condition: the trader must possess infinite capital and access to infinite market liquidity. In the real world, every trader operates under strict capital constraints.
According to the Gambler's Ruin theorem, when an entity with finite wealth engages in a game with continuous risk against an entity with effectively infinite wealth (the global financial market), the probability of eventual bankruptcy for the finite participant approaches 100% as the number of trials increases. Because losing streaks of 8, 10, or 12 trades occur with statistical certainty over a large enough sample size, a Martingale system is guaranteed to hit its capital limit eventually.
Risk 2: Leverage Acceleration and Margin Call Cascades
Position doubling rapidly exhausts usable margin. Leveraged instruments require brokers to hold a portion of account balance as collateral. As trade lot sizes scale exponentially, the margin required to hold open positions grows at the exact same exponential rate.
Once account equity drops below the broker's margin maintenance threshold (e.g., 50% or 30% margin level), the broker automatically triggers a forced stop-out. Instead of having the opportunity to open the next double-sized position to recover, all open trades are closed at maximum drawdown, solidifying total loss.
Risk 3: Structural Market Conditions (Trending Markets vs. Mean Reversion)
Martingale systems implicitly assume that financial markets behave like fair coin flips with independent outcomes. However, market price returns exhibit non-independent distribution characteristics known as fat tails and volatility clustering.
In foreign exchange and futures markets, strong directional trends can persist for hundreds of pips without significant pullbacks. When a Martingale strategy repeatedly places counter-trend trades during a sustained macroeconomic trend or central bank decision, the market will not mean-revert before the trading account runs out of margin. Traders evaluating entry triggers based on technical structures like double tops or head-and-shoulders should first Learn Candlestick Patterns Forex rather than trying to force price reversals through aggressive position scaling.
Risk 4: Liquidity Gaps, Slippage, and Execution Failure
Martingale algorithms often perform flawlessly in backtests that assume continuous price movement and zero execution slippage. Real market execution introduces severe real-world obstacles:
- Weekend Gaps: Currency or index prices can open dozens or hundreds of pips away from Friday's close, bypassing stop levels and jumping past calculation steps.
- Slippage during High-Impact News: Events such as Non-Farm Payrolls (NFP) or interest rate decisions cause market spreads to widen dramatically. Opening a 10-lot position during a liquidity void can lead to massive negative slippage.
- Maximum Order Limits: Liquidity providers and brokers enforce maximum trade lot limits (e.g., 50 lots per ticket). Once a Martingale progression reaches this limit, the strategy cannot complete the required mathematical doubling.
Risk 5: Extreme Asymmetric Risk-To-Reward Dynamic
A balanced trading plan risks a small, controlled percentage of equity to achieve a larger potential gain (e.g., risking $100 to make $200, a 1:2 risk-to-reward ratio). Martingale flips this relationship into an extreme asymmetric dynamic: risking $5,000+ of account balance to secure a nominal gain of $20. A single failure wipes out months or years of accumulated micro-profits.
3. Common Variations of Martingale and Their Hidden Flaws
Recognizing the extreme hazard of strict 2.0x position doubling, retail developers have created hybrid variations. While these adjustments alter the speed of equity depletion, they do not resolve the underlying statistical weakness.
1. Soft / Partial Martingale (Multiplier < 2.0)
Instead of doubling position size (2.0x), soft Martingale utilizes smaller progression multipliers, such as 1.2x, 1.3x, or 1.5x.
The Flaw: While lowering the multiplier slows the rate at which margin is consumed, it requires a larger price movement in the favorable direction to bring the sequence back into net profit. If the market retraces only partially, the position remains stuck in drawdown, accumulating interest and swap fees while continuing to expose the account to systemic risk.
2. Averaging-Down Grid Martingale
Rather than closing a losing trade and opening a larger trade at a new price level, grid Martingale leaves initial losing orders open and adds increasingly larger positions at fixed distance intervals (e.g., every 15 pips against the trend). Traders looking to compare grid mechanics with traditional doubling should Learn Grid Trading Risks to understand floating drawdown dynamics.
The Flaw: Open unrealized losses compound alongside the added position leverage. The combined floating loss grows quadratically, accelerating the distance to a forced liquidation.
3. Short-Term Scalping Martingale
Many automated Expert Advisors use short-term scalping logic on 1-minute or 5-minute charts, attempting to collect 3 to 5 pips per cycle while using Martingale sizing to recover small losses. Traders interested in short-term execution models should Learn Forex Scalping Strategy to discover how precise execution edge replaces sizing tricks.
The Flaw: Low-timeframe market noise routinely produces directional runs that exceed 30 or 40 pips without a 5-pip retracement. The high frequency of micro-trades simply accelerates the occurrence of the eventual fatal sequence.
4. Anti-Martingale (Reverse Martingale)
Anti-Martingale increases position size after winning trades and cuts position size back to base level after a loss.
The Flaw: While Anti-Martingale protects capital during losing streaks, a single loss after a long winning progression can give back a massive portion of accumulated profits if position sizing is scaled too aggressively without locked-in trailing stops.
4. Prop Firm Constraints: Drawdown Limits vs. Exponential Exposure
In modern proprietary trading, risk management rules are designed to protect funded capital from catastrophic events. Understanding how prop firms configure risk parameters highlights why Martingale execution is incompatible with professional capital allocation.
Maximum Daily and Total Drawdown Rules
Most institutional and funded account evaluation models enforce two primary risk boundaries:
- Maximum Daily Drawdown: A fixed or trailing loss threshold evaluated based on daily start-of-day balance or equity (typically between 3% and 5%).
- Maximum Overall / Trailing Drawdown: An absolute cap on equity loss from peak capital (typically between 6% and 10%).
Because Martingale sequences experience non-linear equity drops during consecutive losses, even a minor losing run (3 to 4 steps) will instantly breach daily loss limits, causing immediate evaluation failure or account termination.
Program Structure Breakdown
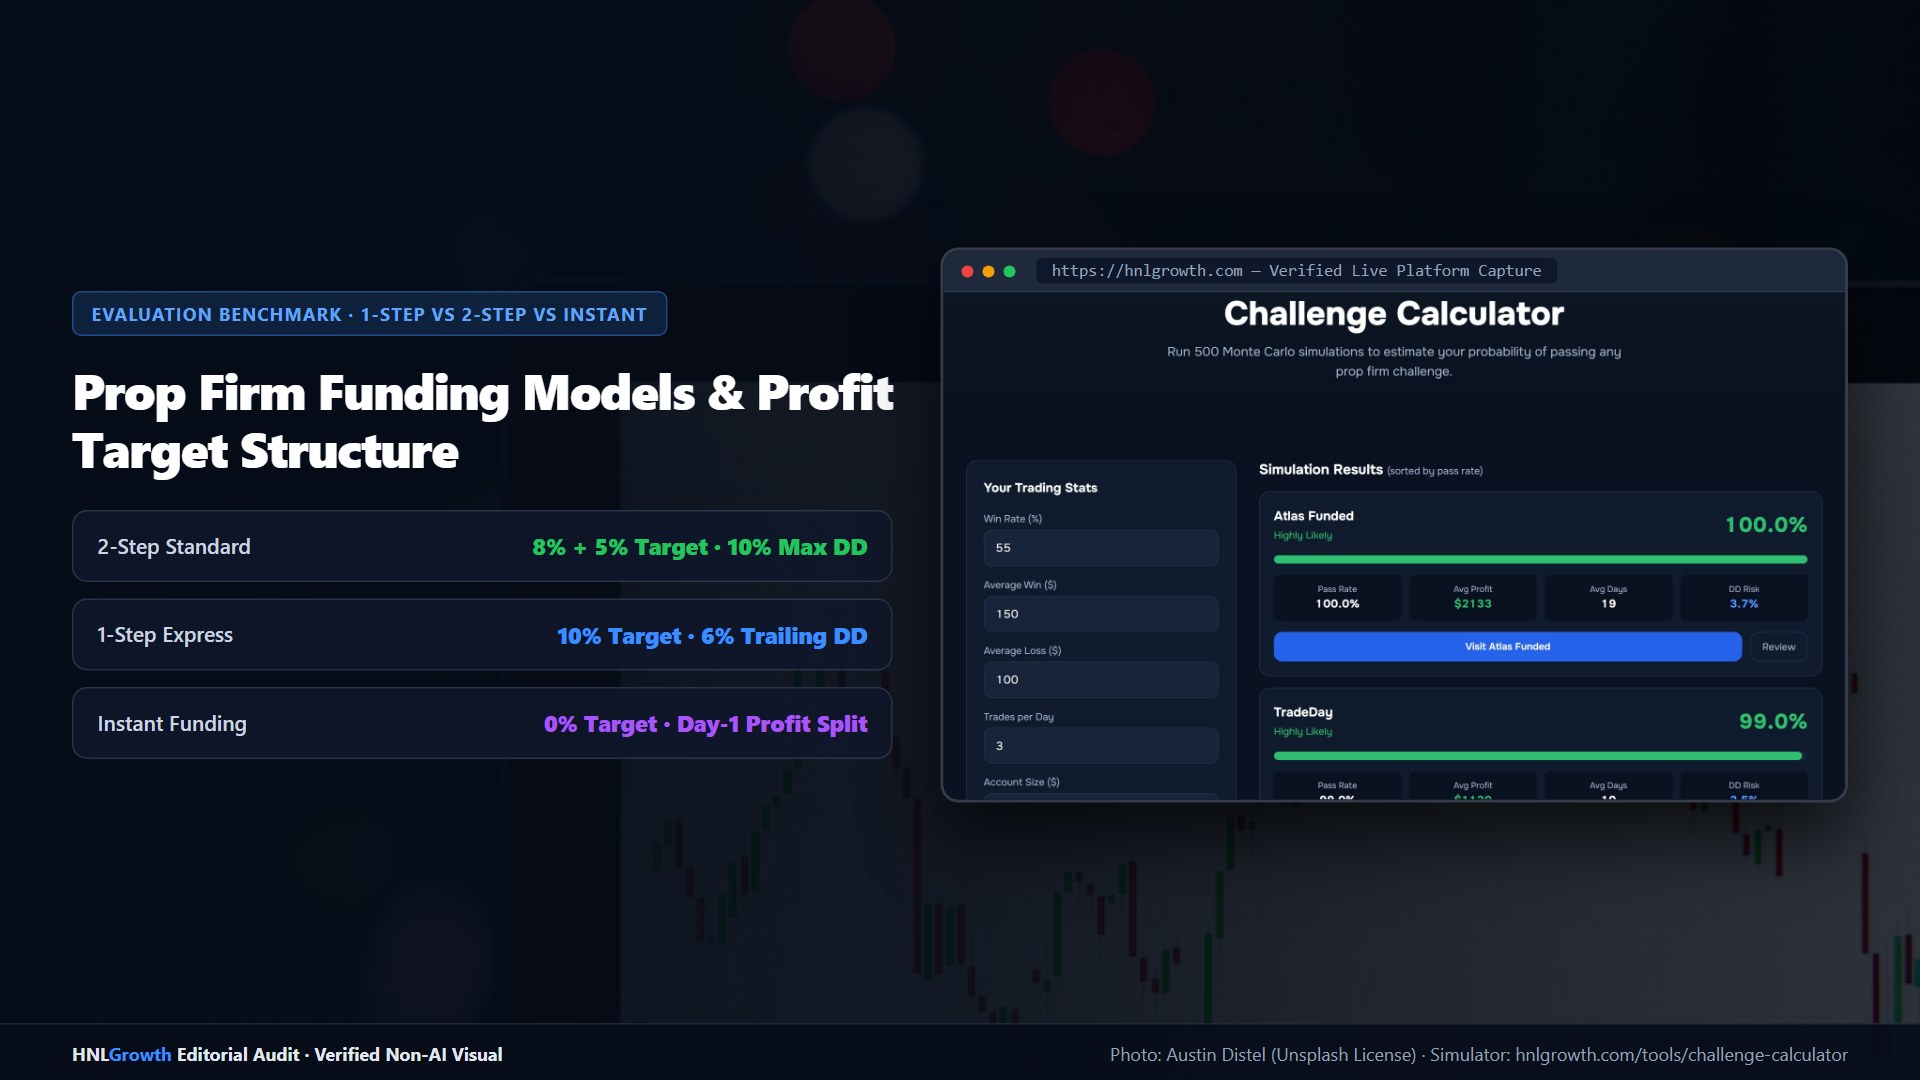
When reviewing professional funding evaluation tracks, execution consistency and strict position sizing are key parameters across simulated environments:
- High Stakes Program: Features a structured two-step evaluation model with strict program-specific profit targets and maximum daily/total loss limits that render unhedged position doubling unfeasible.
- Bootcamp Program: A three-stage qualification route designed to evaluate long-term risk management and consistent position sizing under designated funded-stage rules.
- Hyper Growth Program: A streamlined one-step growth framework emphasizing disciplined risk parameters, fixed leverage controls, and strict asset-class risk limits.
- Futures Options: Programs structured around Day Trade and Swing models incorporating end-of-day (EOD) loss-limit guidelines and consistency criteria to prevent sudden account liquidation.
5. Replacing Martingale with Fixed Fractional Sizing and True Expectancy
Professional traders build long-term profitability by developing a positive statistical expectancy while controlling downside risk through disciplined position sizing.
1. Fixed Fractional Position Sizing
Instead of scaling lot sizes up after a loss, fixed fractional sizing risks a constant, small percentage of current equity on every trade (e.g., 0.5% or 1.0% per trade). Under fixed fractional sizing:
- When account equity decreases during a losing streak, the absolute dollar amount risked on the next trade automatically decreases.
- This preserves account capital, allowing a trader to survive 20, 30, or 50 consecutive losses without burning the account.
2. Calculating True Mathematical Expectancy
To determine if a trading setup offers a real edge without relying on sizing tricks, calculate trade expectancy ($E$) using the formula:
E = (Win Rate × Average Win) - (Loss Rate × Average Loss)
Example Comparison:
- Martingale Model: 95% Win Rate × $10 Average Win = $950 gain. But 5% Loss Rate × $20,000 Average Loss = -$1,000. Net Expectancy = -$50 per trade sequence.
- Disciplined Systematic Model: 40% Win Rate × $300 Average Win ($120) - 60% Loss Rate × $100 Average Loss ($60). Net Expectancy = +$60 per trade over time.
Risk Audit Checklist for Strategy Execution
Before deploying any strategy live, verify that your rules satisfy these criteria:
- Every trade has a pre-defined stop loss established before order execution.
- Risk per trade is capped at a fixed percentage of equity (≤ 1% recommended).
- Position sizing scales down during drawdowns, not up.
- Reward-to-risk ratio per trade is at least 1:1.5 or 1:2.
- Max daily equity loss limits are respected regardless of strategy signals.
Five Forex Constraints That Break the Theory
Most martingale explanations use casino analogies. Forex introduces five mechanical constraints that those examples ignore entirely.
Spread Cost Compounds With Every Doubling
Spread is paid per lot traded. As lot size doubles, so does the dollar cost of the spread. On EUR/USD with a 1.2-pip spread, the first trade costs $0.12 in spread; the seventh trade costs $7.68. Total spread paid across seven losing trades: $15.24.
The recovery trade at 1.28 lots pays another $15.36 in spread. That means $30.60 in total spread cost to chase a $0.20 target profit. Spread acts like a house edge — it compounds against you with each step and erodes the net recovery even when the sequence eventually wins.
Margin Call and Stop-Out as Hard Ceilings
Brokers automatically close positions when your margin level falls below a defined stop-out threshold. According to the published account specifications, HFM's Zero, Pro, and Premium accounts carry a margin call at 50% and a stop-out level at 20%. The InfinityX account operates differently, with margin call at 20% and stop-out at 0%.
On a $1,000 Pro account using 1:2000 leverage (the maximum available according to the HFM trading-accounts page), the sequence survives seven doublings before the eighth triggers stop-out. At that step, the required margin for 1.28 lots ($70.40) pushes the margin level below 100% after the cumulative $255.60 in losses.
Doublings Before Stop-Out: By Account Size and Leverage
The table below shows how many consecutive doublings survive before stop-out, using a 0.01-lot start with 20-pip losses. Calculations use the standard margin formula: Required Margin = (Lot Size × 100,000 × Price) / Leverage, with EUR/USD at 1.1000.
| Account size | 1:100 leverage | 1:500 leverage | 1:2000 leverage |
|---|---|---|---|
| $500 | 4 | 5 | 5 |
| $1,000 | 5 | 6 | 7 |
| $5,000 | 8 | 9 | 9 |
Even at maximum leverage on a $5,000 account, the sequence terminates after nine consecutive losses. Higher leverage extends the sequence by one or two steps but magnifies the terminal loss when it arrives.
Maximum Lot-Size Limits Cap the Sequence
According to the published HFM account specifications, most account types impose a maximum of 60 standard lots per position. The Cent account is limited to 1,000 Cent lots per position (equivalent to 10 standard lots).
Starting from 0.01 standard lots, the doubling sequence reaches 60 lots at step 13. In practice, margin exhaustion stops the sequence long before this on any standard-sized account. On the Cent account, however, the 1,000-lot per-position cap (step 7 equivalent) may constrain the sequence earlier than margin alone would dictate, depending on account equity.
Leverage: More Doublings, Bigger Terminal Loss
Leverage reduces the margin required per position, allowing more doublings. But it does not reduce cumulative losses — those grow identically regardless of leverage. Moving from 1:100 to 1:500 on a $1,000 account adds one doubling (from five to six), but the terminal loss at step six is $12.60 and at step seven is $25.40. Leverage extends the runway; it does not change the destination.
Slippage During Volatile Sessions
During major news releases and market-open windows, execution prices deviate from quoted prices. On a 0.01-lot trade, one pip of slippage costs $0.10. On the 1.28-lot recovery trade, that same pip costs $12.80 — more than the entire target profit of the sequence. Slippage is unmodelled in any static martingale calculation and worsens proportionally with position size.
How the Martingale Sequence Works in Forex
The martingale system follows a single rule: after each losing trade, open the next position at double the previous lot size. When a trade finally wins, the larger position recovers every prior loss in the sequence plus a profit equal to one base unit.
In forex terms, start with 0.01 lots (one micro lot) on EUR/USD. Each trade targets a 20-pip stop loss. When the trade loses, the next position doubles to 0.02 lots, then 0.04, 0.08, and so on. At 1:1 payoff, the winning trade's pip gain should cover all accumulated losses plus $0.20 — the dollar value of 20 pips on the original 0.01 lot.
The table below walks through seven consecutive losses on EUR/USD, assuming a 1.2-pip spread:
| Step | Lot size | Trade loss (20 pips) | Cumulative loss | Spread cost (1.2 pips) |
|---|---|---|---|---|
| 1 | 0.01 | $0.20 | $0.20 | $0.12 |
| 2 | 0.02 | $0.40 | $0.60 | $0.24 |
| 3 | 0.04 | $0.80 | $1.40 | $0.48 |
| 4 | 0.08 | $1.60 | $3.00 | $0.96 |
| 5 | 0.16 | $3.20 | $6.20 | $1.92 |
| 6 | 0.32 | $6.40 | $12.60 | $3.84 |
| 7 | 0.64 | $12.80 | $25.40 | $7.68 |
The recovery trade — step 8 at 1.28 lots — needs 21 pips of favourable movement to cover all seven losses, all spread costs, and deliver the $0.20 target profit. That extra pip beyond the standard 20 exists because cumulative spread across the sequence erodes the recovery margin.
6. Conclusion and Strategic Recommendations
Martingale trading is ultimately a mathematical illusion. By doubling position sizes after losses, traders transform small trade-level risks into systemic account failure risks. While it may mask poor entries or weak trade timing over brief backtests, the inevitable arrival of a prolonged directional trend or liquidity gap results in rapid account liquidation.
Sustainable trading success requires shifting focus away from sizing manipulation and toward structural market edges, risk discipline, and positive statistical expectancy.
Further reading: ESMA Investor Corner · FINRA investor insights.
Martingale Trading Risks: Your Questions Answered
Why is Martingale so popular among Forex EA developers?
Martingale strategy EAs are easy to market because they generate near-linear backtest equity curves with high win rates (often 90% to 98%). Marketing materials can showcase months of consistent daily gains while hiding the fact that a single tail-risk event will wipe out 100% of the account capital.
Can Martingale work if I have a very large account balance?
No. Having a larger capital base only delays the failure point—it does not prevent it. Because position sizes grow exponentially ($2^n$), adding $100,000 to an account balance might only allow the strategy to survive 3 or 4 additional losing trades in a sequence before total margin is exhausted.
Are Martingale strategies permitted in prop firm evaluations?
Most proprietary trading firms strictly restrict or disallow aggressive Martingale execution, position multiplication, and unhedged drawdown stacking. Also, strict daily and overall drawdown limits ensure that an escalating Martingale sequence will trigger an account breach long before recovering.
What is the difference between Martingale and Grid Trading?
Martingale specifically refers to scaling up position size (usually doubling) after a loss. Grid trading involves opening buy or sell orders at regular price intervals. However, many grid EAs combine both approaches—opening increasingly larger orders as price moves against the grid—creating severe compound risk.
How can I recover an account that suffered drawdowns from Martingale trading?
The first step is to halt all automated Martingale scripts or doubling rules immediately. Transition to fixed fractional risk sizing (risking no more than 0.5% to 1% per trade), audit your setup for positive expectancy, and rebuild equity steadily through consistent risk-to-reward management.
Compare Funded Programs That Fit This Trading Style →
Related The5ers Guides
- Monthly Subscription vs One-Time Prop Firm Fees: Total Cost Compared
- News Trading Risk Management: Slippage, Spreads, and Event Windows
- Overleveraging in Trading: How Large Lot Size Destroys Good Strategies
Related Guides
Sources & verification
- Last checked
- Written by
- HNL Growth Team
- Reviewed by
- Hà Ngọc Lộc
- Length
- 14 min read · 3,186 words
Rules, prices and payout terms on this page were checked against the official websites, help-centre articles and published terms of the firms mentioned, on the date above. Prop firms and brokers change conditions often — confirm the current version on the official site before you buy or deposit. Read our editorial methodology and affiliate disclosure.
Official sources & documentation verified
- ESMA Investor Corner(esma.europa.eu · Official Regulator)
- FINRA investor insights(finra.org · Official Regulator)
Explore Related Hubs & Free Trading Tools
Ready to Start Your Funded Trading Journey?
HashHedge reports $11M+ paid to traders and lists a 4.7/5 Trustpilot rating (check current figures on Trustpilot). Compare HashHedge challenge plans, drawdown rules, and payout terms — apply code ha25 for the current discount.
Risk disclaimer: Challenge fees are non-refundable if you breach the rules. Prop trading involves significant financial risk. Past performance in a simulated environment does not guarantee results on a funded account. Only purchase if you understand the rules fully and can afford to lose the fee. Affiliate disclosure: HNL Growth earns a commission when you purchase a HashHedge challenge through links on this page.